


Legal Briefing
Answers to the Questions Korean Companies Most Frequently Ask Before Establishing a US Corporation.
We have compiled and answered the questions that Korean companies most frequently ask during incorporation consultations regarding establishing a US corporation, particularly when setting up a local subsidiary in the United States.
1. When establishing a US corporation, which structure is more suitable — a subsidiary or a branch office?
If you are considering establishing a US corporation, choosing a subsidiary structure is advantageous in order to completely shield the Korean headquarters from tax and litigation exposure while conducting business.
Comparison Item | US Subsidiary | Branch |
Legal personality | An independent legal personality separate from the headquarters | An extension of the headquarters (no independent legal personality) |
Inclusion of the headquarters in US tax jurisdiction | Not included (as a general rule) | Directly included in the tax jurisdiction |
Headquarters' US tax filing obligation | None as a general rule | Filing of a US tax return is required |
Main taxable items | Corporate income tax (21%) + dividend withholding tax | Corporate income tax (21%) + branch profits tax (30%) |
Headquarters' liability for legal debts | Limited liability protection (blocked as a general rule) | The headquarters bears full legal liability |
2. In which US state is it best to establish a corporation?
Before establishing a US corporation, when deciding which US state to choose, you should consider the following three aspects together.
- Delaware: Thanks to its flexible corporate law framework, high predictability based on accumulated case law, swift registration processing, and the high level of expertise among US attorneys, it is chosen by more than 66% of Fortune 500 companies and more than 81% of publicly listed companies.
- Other states (Nevada, Texas, Wyoming, etc.): Their popularity is rising on the strength of favorable state tax systems, strong privacy protection, and low regulatory burdens.
- The state of actual business operations (the most decisive criterion): If you establish the corporation directly in the state where you actually conduct business, you can avoid the duplicate costs and administrative burdens of registering to do business in other states. For a single-region business that does not serve the entire United States and has no plans to attract outside investment, it is advisable to give priority to the location of business operations. (※ Because the choice of the state of incorporation does not directly affect federal tax or state income tax burdens, choosing the state of incorporation solely to reduce taxes is not justified.)
Establishing a corporation in Delaware requires separate registration in other states
If you establish a corporation in Delaware but the state where you actually conduct business is different, then even though legal personality is created upon filing the certificate of incorporation, you must separately complete business registration in the state where you actually conduct business.
This also entails costs of several hundred dollars per year and an annual reporting obligation.
Furthermore, in some states, business registration itself may be deemed consent to the general jurisdiction of that state's courts, so a prior review is necessary from the standpoint of managing litigation risk as well.
3. What are the criteria for deciding the form of a US corporation?
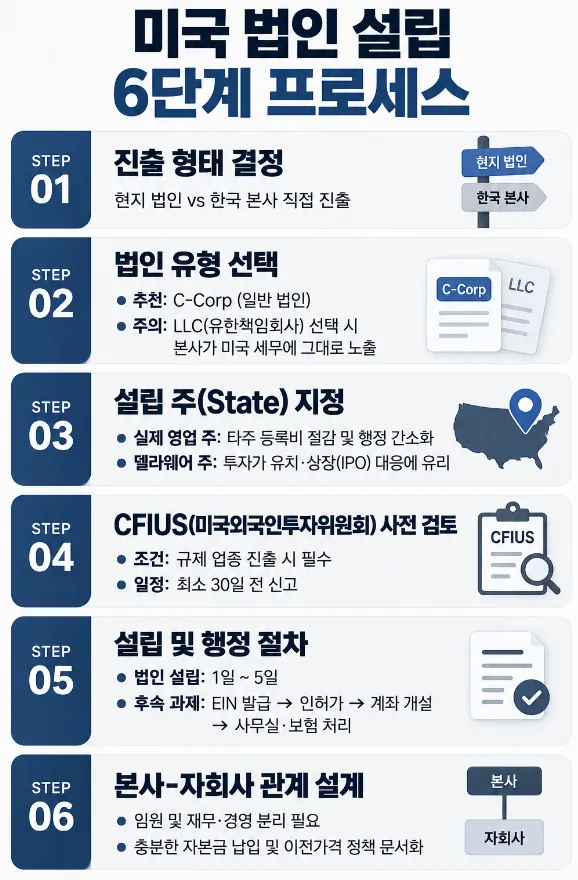
When advising on establishing a US corporation, we recommend a C-Corporation (hereinafter "C-Corp") as the default.
From the Korean parent company's standpoint, it is only natural not to want the headquarters directly exposed to US tax jurisdiction and tax filing obligations, so a C-Corp subsidiary, which is an opaque entity for tax purposes, should be chosen.
If an LLC is chosen as a pass-through entity, the LLC's US business is attributed directly to the Korean parent company, so the Korean headquarters itself files and pays US corporate income tax and even a 30% branch profits tax will have to be borne.
Except in special structures where large losses are expected during the first several years of business and loss aggregation for Korean tax purposes is needed, choosing a C-Corp is appropriate.
Immediate commencement of business is not possible upon incorporation
When establishing a US corporation, acceptance of the certificate of incorporation itself is completed within 1–3 days, but the following subsequent procedures are required before actual business operations can begin.
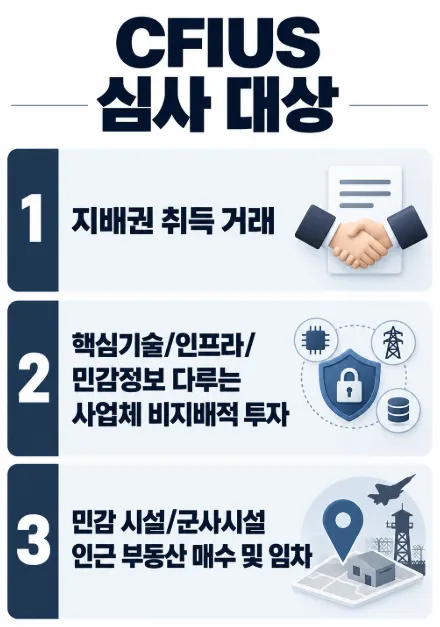
4. What risks frequently arise in the relationship between a Korean headquarters and its US subsidiary?
After establishing a US corporation, the biggest risk is that problems at the subsidiary drag the Korean headquarters in as a party to US litigation.
- Risk factors: Failure to observe corporate formalities (not holding board or shareholder meetings), excessive undercapitalization of the subsidiary, commingling of funds/employees between the parent and the subsidiary, and operating the subsidiary as a mere instrument of the parent company
- Response principles: You must strictly maintain separate accounting/bank accounts in the subsidiary's name, compose the board of directors distinctly from the parent company, and faithfully pay in initial capital commensurate with the scale of operations. (※ Involvement at the level where the parent company, in its capacity as an investor, supervises the subsidiary's finances and provides general management direction is recognized as a legitimate exercise of authority.)
- Tax risk: For transactions of goods, services, and funds between the parent and the subsidiary, you must maintain meticulous documentation so that transfer prices comply with the arm's length principle.
From incorporation through local regulatory compliance, together with Daeryun
Daeryun provides advisory services through a US-incorporation advisory team composed of numerous foreign attorneys (US) licensed in states such as New York and Washington, D.C., together with corporate-law specialist attorneys, tax accountants, patent attorneys, and labor attorneys.
In addition, we directly operate a local law firm in New York, USA, and have built a one-stop system that links Korea and the US in real time, so we provide advice for a stable entry into the US market — from complex local licensing and permitting issues to governance design and the mitigation of labor and tax risks.
The licensing review points that must be checked before commencing local business in the US, as well as the state laws and essential regulations you will encounter when operating a local business site, and analyses of important case law on litigation jurisdiction after establishing a US corporation, can be downloaded for free through the link below.


Enter the information below and we will email you a detailed report related to what you are reading.
This content is based on actual cases handled by Daeryun Law LLC and has been partially adapted. All copyrights belong to Daeryun Law LLC.
Unauthorized reproduction, copying or distribution may result in legal action under applicable laws.
Related Information
Explore legal information related to this case.
Establishing a Holding Company: Structure and Procedure
Matters to Confirm When Carrying Out the Procedure for Establishing an Incorporated Foundation
Procedures for Establishing an Overseas Branch and Points to Check When Establishing a Local Subsidiary
Daeryun's Key Strengths


Litigation strategy using Daeryun's own AI & IT technology

More than 240 key members

1,200+ cases handled per month
* 2025년 월평균 기준
Complies with Korean Bar Association Advertising Regulations Article 4 (1)
more strengths

Book a legal
consultation with an attorney
All consultations are reviewed by a specialized attorney first,
so they are conducted by appointment only.
Phone consultation
1800-7905
Available 24 hours a day, 365 days a year


Online consultation
We provide tailored
legal services for our clients.

Chat consultation
KakaoTalk channel
Daeryun Law LLC Attorneys
Related Members
View more
KyeongWeon YUN
T. 070-5117-3709
Experience as a diplomatic counselor at the Korean Embassy in China and as a human rights policy officer at the Supreme Prosecutors' Office

SeJun KIM
T. 070-5221-0865
Experience as judge at Seoul Southern District Court and Daejeon District Court



Related Practice Areas
View moreConsult in other languages


Popular Columns
View moreHow to Register a Quasi-Investment Advisory Business, and Points to Note When Providing Stock Tips

Copyright Infringement: Severity of Punishment, Damages, and Response Methods
The Meaning of Corporate Rehabilitation Proceedings, the Measures Involved, and Points Requiring Caution
The Effect of a Non-Disclosure Agreement, Liability for Breach, and Key Points to Know When Drafting One
Compliance Obligations Under the Fair Transactions in Franchise Business Act and Cases of Violation
Do you have more questions?






