


Deals & Cases
Violation of the Punishment of Tax Evaders Act | Case Securing a Fine on a Charge of Violating the Act
This is the story of a client who faced the risk of criminal punishment for a violation of the Punishment of Tax Evaders Act. A Daeryun attorney set about providing assistance, and succeeded in concluding the charge of violating the Punishment of Tax Evaders Act with a fine.
1. The Client Who Sought Help on a Charge of Violating the Punishment of Tax Evaders Act
This is the story of a client who requested help on charges of violation of the Punishment of Tax Evaders Act and issuance of false tax invoices.
The client had in the past, at the recommendation of an acquaintance, been registered as the representative in the name of a distribution company.
Outwardly, the corporation appeared to be a business engaged in intermediate wholesale distribution, but in substance it was a paper company that existed in name only, without any human or physical facilities.
The acquaintance proposed that the client lend his name, saying, "You do not need to be involved in running the company, and you can receive a fixed amount each month."
The client, without much suspicion, established the corporation in his name as the representative, and thereafter, for about one year, cooperated in the work of exchanging tax invoices totaling about 3 billion won with outside business operators.
The problem was that all of these tax invoices were issued without any actual transactions.
These tax invoices were used by other business operators for purposes such as expense processing and deduction of input tax, and the tax authorities regarded the client as a 'person who exchanged tax invoices without an actual supply of goods or services' and brought a criminal indictment on charges of issuing false tax invoices under the Punishment of Tax Evaders Act.
The Concept of Issuing False Tax Invoices and Violating the Punishment of Tax Evaders Act
The tax invoice system is a system established under the Value-Added Tax Act so that, when goods or services are supplied, a business operator transparently reports the transaction details.
Accordingly, issuing or receiving a tax invoice for a transaction in which there is no actual supply is plainly unlawful.
What is a 🔗false tax invoice?
A false tax invoice means a tax invoice issued as if a transaction had taken place when in fact no transaction occurred, or a tax invoice issued with an amount recorded differently from the actual amount.
-Issued as if a transaction that did not actually occur had taken place
-A tax invoice issued with an amount recorded as more or less than the actual amount
If the issuance of a false tax invoice exceeds a certain supply value, it is regarded not as a simple violation of the Value-Added Tax Act but as a ‘specific crime,’ and a heavier criminal liability may be imposed.
2. Establishing a Strategy to Defend Charges Including Violation of the Punishment of Tax Evaders Act
We set about devising a strategy to defend against allegations such as a violation of the Punishment of Tax Evaders Act and issuance of false tax invoices.
Daeryun LLC formed a task force of specialist attorneys with experience in numerous related cases and devised a strategy by focusing its analysis on the circumstances of the tax invoice issuance and the client's situation at the time.
Arguing That the Client Was Unaware of the Law
The client was a layperson with no expertise in accounting at all, and issued the tax invoices relying solely on what the personnel of company B said.
In fact, the client was reassured by statements such as “just issue the invoices and we will take care of the rest” and “we are responsible for the taxes,” and there were also circumstances showing that company B had, without any actual transaction, contrived a scheme of transferring the payment and then refunding it.
Through this, the tax attorney strongly argued that A had not intended to evade taxes intentionally.
Organizing How the Statements Came to Be Made and Clarifying the Facts
In the early stage of the tax investigation, the client came to make false statements after believing the words of the representative of Company B, who induced him by saying, “If you take all the blame, I will pay the taxes on your behalf.”
Afterward, when contact with Company B was lost, he belatedly realized that he had been used, and in the course of the investigation he stated all the facts honestly.
The tax attorney explained in detail that this change in the course of the statements was not a mere retraction, but resulted from the reality the client faced at the time and from the deception of a third party.
In particular, the attorney emphasized that there was doubt as to the credibility and prudence of the initial statements, and that the client had actively cooperated by setting out the specific facts one by one in his later statements, thereby emphasizing that the client had participated faithfully in the investigation.
Active Assertion of Grounds for Mitigation
The tax attorney argued that the client, due to an unprecedented economic downturn, had reached a point where business operations were nearly suspended, and that the client received a tempting offer from Company B in a desperate situation in which he could not even afford employee wages and rent.
In particular, the attorney explained, with supporting materials, that the client did not obtain a direct tax benefit, that he received only part of a commission in return for issuing the tax invoices, and that there were even circumstances in which he in fact suffered a loss for some portion, and requested leniency.
Asserting the Efforts Made to Repair the Harm
The tax attorney emphasized that the client had paid part of the value-added tax imposed due to the issuance of false tax invoices and was making efforts toward substantial recovery of the harm.
The attorney also emphasized that the client planned to pay the remaining value-added tax in monthly installments and requested leniency.
3. Result of Assisting the Client Charged With Violation of the Punishment of Tax Evaders Act and Other Offenses
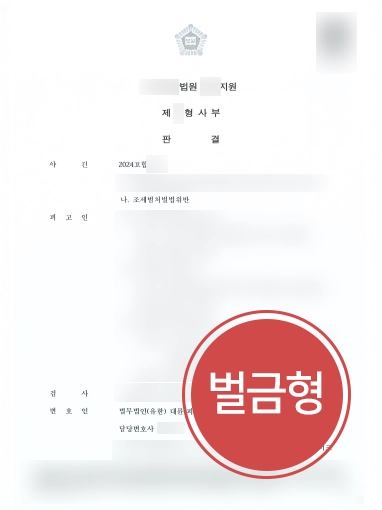
As a result of defending the client charged with violating the Punishment of Tax Evaders Act, the court imposed a fine.
The court rendered this decision taking into account that the client ▲did not take part in the tax evasion in a leading role, and ▲the benefit obtained by the client was relatively minor in light of the content, scale, and the like of the false tax invoices.
The client said, “I was truly afraid that I would receive a severe punishment. Thanks to the specialist attorney's defense, I was able to conclude the case with a fine.”
Charge of Violating the Punishment of Tax Evaders Act: Why an Attorney's Help Is Needed
Cases related to violation of the Punishment of Tax Evaders Act involve complex legal principles and procedures that are difficult for an ordinary person to readily understand or respond to.
The Punishment of Tax Evaders Act determines whether to impose punishment by comprehensively judging various factors, such as the purpose of issuing the tax invoice, whether an actual tax return was filed, and the status of tax payment.
Accordingly, it is very important to establish an appropriate response strategy from the early stage of the case through the assistance of an attorney well versed in the relevant law.
Daeryun LLC provides case-tailored legal response strategies by forming a task force composed of attorneys with extensive experience in tax and criminal cases such as violations of the Punishment of Tax Evaders Act, together with a tax accountant belonging to the firm.


Check out video content
related to this case as well.

Meet Daeryun’s tax administration expert
This content is based on actual cases handled by Daeryun Law LLC and has been partially adapted. All copyrights belong to Daeryun Law LLC.
Unauthorized reproduction, copying or distribution may result in legal action under applicable laws.


Issuance of false tax invoices, etc.: Want a faster, more detailed consultation?
Consult aspecialized attorney
Related Information
Explore legal information related to this case.
The Level of Punishment for Lending One's Name and How to Respond to Business Name Lending
Extinction of National Tax Arrears: Standards and a Summary of the Extinctive Prescription of National Taxes
Tax Litigation: Response Strategies to Avoid Fines from a Tax Investigation
Daeryun's Key Strengths


Litigation strategy using Daeryun's own AI & IT technology

More than 240 key members

1,200+ cases handled per month
* 2025년 월평균 기준
Complies with Korean Bar Association Advertising Regulations Article 4 (1)
more strengths

Book a legal
consultation with an attorney
All consultations are reviewed by a specialized attorney first,
so they are conducted by appointment only.
Phone consultation
1800-7905
Available 24 hours a day, 365 days a year


Online consultation
We provide tailored
legal services for our clients.

Chat consultation
KakaoTalk channel
Daeryun Law LLC Attorneys
Related Members
View more

Key Case Studies
View moreRelated Practice Areas
View moreConsult in other languages


Popular Columns
View moreTypes and Subjects of Tax Audits, Procedure and Duration, and How to Respond to an Audit

Understanding the Penalty Levels for Lending a Business Name and Lending Between Family Members
Issuing and Receiving False Tax Invoices: From Punishment to How to Respond
Tax Evasion Punishment: Types of Conduct Subject to Punishment, Severity, and Response Methods
National Tax Service Tax Investigations: Targets and the Investigation Procedure

Previous
Bodily Injury Complaint Defense Case | Acquittal for a Client Charged With Infliction of Bodily Injury
Next
Traffic Accident Firm Defense Case | Retaliatory Driving and Special Intimidation, Non-Prosecution
View list
Do you have more questions?






