


Deals & Cases
Tax Attorney Case Example | Issuance of False Tax Invoices Worth 3 Billion Won, Acquittal
The client who sought out a tax attorney operated both a corporate business and a sole proprietorship, and was in a situation requiring assistance after being indicted by the prosecution on charges including the issuance of false tax invoices.
1. The Client Who Sought Out a Tax Attorney
This is a case in which, with the assistance of a tax attorney, the client, who had faced the risk of punishment on suspicion of issuing false electronic tax invoices exceeding 3 billion won, established his innocence.
The Charges Applied to the Client
The client was a businessman engaged in the manufacture of mobile phone components who initially operated a sole proprietorship and later established a corporation, operating both businesses together.
However, the prosecution took the view that the client had falsely issued 7 electronic tax invoices worth 3 billion won between the sole proprietorship and the corporation over a period of about 3 months, despite there having been no actual transactions.
The Prosecution's Argument
- Tax invoices were exchanged as a formality even though no actual goods or services were exchanged
Accordingly, the client was charged with a violation of the Act on Aggravated Punishment of Specific Crimes, and if found guilty, he was at risk of receiving a heavy sentence.
The Client's Assertion
The client, however, presented an entirely different position.
The Client's Rebuttal
- Employees were actually hired to produce and supply parts
- The tax invoices were issued in the course of ordinary transactions
To clear this injustice and prevent an unwarranted penalty, the client ultimately retained a tax law attorney to handle the case.
2. False Tax Invoices Explained by a Tax Attorney
The principal charge in this case, handled by the tax attorney, was the issuance of a 'false tax invoice' and related conduct.
Issuing or receiving a false tax invoice is an offense that seriously undermines tax order, and it is strictly punished under the "Punishment of Tax Evaders Act" and the "Act on Aggravated Punishment of Specific Crimes."
Prohibited Conduct Under the Punishment of Tax Evaders Act
Article 10, Paragraph 3 of the Punishment of Tax Evaders Act clearly prohibits 'issuing or receiving a tax invoice, or submitting an aggregate table with false entries, even though no actual supply of goods or services has taken place.'
A violation may result in the following punishment.
Statutory Provision | Level of Punishment |
Punishment of Tax Evaders Act, Article 10, Paragraph 3 | Imprisonment for not more than 3 years, or a fine not exceeding three times the tax amount on the false supply value |
The client, too, was suspected by the prosecution of having 'falsely exchanged tax invoices worth approximately 3 billion won between an individual business and a corporation despite the absence of any actual transactions,' and criminal punishment was accordingly anticipated.
Aggravated Punishment Under the Act on Aggravated Punishment of Specific Crimes
In particular, because the total supply value of the tax invoices at issue exceeded 3 billion won, the "Act on Aggravated Punishment of Specific Crimes" applied to the client.
This Act provides that where false tax invoices are issued for profit, a custodial sentence of at least one year is to be imposed depending on the scale of the supply value, so the level of punishment is very severe.
Aggregate Supply Value, etc. | Level of Punishment |
50 billion won or more | Imprisonment for a definite term of at least 3 years |
30 billion won or more but less than 50 billion won | Imprisonment for a definite term of at least 1 year |
In addition to such punishment, a fine of not less than twice and not more than five times the tax amount calculated by applying the value-added tax rate to the aggregate supply value, etc., is also imposed.
Accordingly, if the client failed to establish his innocence, he could face both a custodial sentence and a substantial fine.
3. Assistance Provided by the Tax Attorney
To defend the client's position, the tax attorney closely analyzed the case records and transaction history and submitted to the court various materials capable of establishing that actual transactions had taken place.
In that process, the following defense strategy was pursued.
Tax Attorney's Strategy 1 | Establishing the Existence of Substantive Transactions
The prosecution claimed that the two businesses had exchanged tax invoices in a merely formal manner, but the tax attorney presented as evidence the fact that employees had actually been hired, products had been manufactured, and a factory and equipment had been operated.
Furthermore, relying on the monthly transaction statements and shipment records, the attorney emphasized that the issuance of the tax invoices was the result of ordinary transactions.
Tax Attorney's Strategy 2 | Emphasizing the Independence of the Businesses' Operations
Although the business premises of the two enterprises were located within the same building, it was established that they were operated as substantively separate spaces.
In addition, by establishing that the employees had been formally hired in accordance with the corporation's personnel and payroll systems, the attorney explained that the two businesses were not merely nominal organizations for tax avoidance.
Tax Attorney's Strategy 3 | Developing the Defense Argument on Legal Grounds
The tax attorney analyzed the elements of the false tax invoice offense set out in the "Punishment of Tax Evaders Act" and the "Act on Aggravated Punishment of Specific Crimes" and pointed out that the premise of 'the absence of an actual transaction' was not satisfied.
In other words, contrary to the facts charged, the attorney argued persuasively, on legal grounds, that an actual supply of goods and services had taken place and that the conduct therefore did not constitute the issuance of a false tax invoice.
4. Acquittal Following the Assistance of a Tax Attorney
Through the tax attorney's oral argument and the systematic submission of documentary evidence, the court recognized the actual supply of goods and the independent operation of the business.
Summary of the Court's Determination
▶ The two businesses had the requisite human and physical foundations and were operated independently
▶ No intent that would constitute the offense of issuing false tax invoices was found
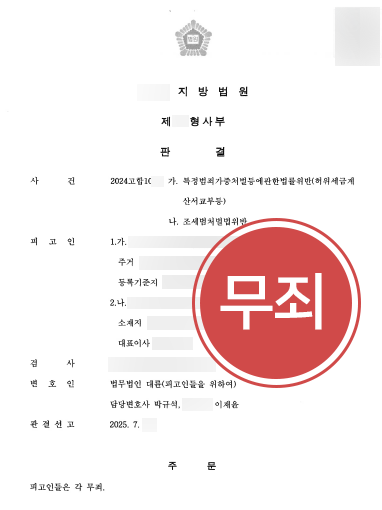
Accordingly, the charges of issuing false tax invoices and related allegations against the client resulted in an acquittal, and the client was able to avoid the risk of a substantial fine and an actual custodial sentence.
How to Respond to a Tax-Related Criminal Case
In cases such as the issuance and delivery of false tax invoices, securing materials that can prove the existence of the actual transactions is the key issue, and the defense argument must be systematically constructed by analyzing the case record.
It is also important to carefully examine whether there was any excessive application of the law or distortion of the facts during the prosecution's investigation.
Daeryun LLC brings together 🔗tax law specialist attorneys, certified public accountants, certified tax accountants, and various other professionals.
This makes it possible to pursue an active response aimed at preventing an unjust punishment, including proving the substance of the transactions, demonstrating the independence of the business operations through analysis of accounting records, and establishing a trial strategy.
If you are involved in a tax-related criminal case and require assistance, we invite you to entrust your case to us through a 🔗legal consultation booking.
This content is based on actual cases handled by Daeryun Law LLC and has been partially adapted. All copyrights belong to Daeryun Law LLC.
Unauthorized reproduction, copying or distribution may result in legal action under applicable laws.


Violation of the Act on Aggravated Punishment of Specific Crimes (issuance of false tax invoices, etc.): Want a faster, more detailed consultation?
Consult aspecialized attorney
Related Information
Explore legal information related to this case.
Statute of Limitations Under the Act on Aggravated Punishment of Specific Economic Crimes: The Level of Punishment and the Limitations Standard by Amount of Gain
The Level of Punishment for Lending One's Name and How to Respond to Business Name Lending
Extinction of National Tax Arrears: Standards and a Summary of the Extinctive Prescription of National Taxes
Daeryun's Key Strengths


Litigation strategy using Daeryun's own AI & IT technology

More than 240 key members

1,200+ cases handled per month
* 2025년 월평균 기준
Complies with Korean Bar Association Advertising Regulations Article 4 (1)
more strengths

Book a legal
consultation with an attorney
All consultations are reviewed by a specialized attorney first,
so they are conducted by appointment only.
Phone consultation
1800-7905
Available 24 hours a day, 365 days a year


Online consultation
We provide tailored
legal services for our clients.

Chat consultation
KakaoTalk channel
Daeryun Law LLC Attorneys
Related Members
View more
KyuSeok PARK
T. 070-7510-1044
Prosecutor experience at Seoul Southern District Prosecutors’ Office and Busan District Prosecutors’ Office

Key Case Studies
View moreRelated Practice Areas
View moreConsult in other languages


Popular Columns
View moreTypes and Subjects of Tax Audits, Procedure and Duration, and How to Respond to an Audit

Understanding the Penalty Levels for Lending a Business Name and Lending Between Family Members
Issuing and Receiving False Tax Invoices: From Punishment to How to Respond
Tax Evasion Punishment: Types of Conduct Subject to Punishment, Severity, and Response Methods
National Tax Service Tax Investigations: Targets and the Investigation Procedure

Previous
Defense Against a Violation of the Act on Special Cases concerning the Settlement of Traffic Accidents | Suspension of Indictment for the At-Fault Client
Next
Subsidy Act Violation Defense Case | Acquittal of a Client Charged With Violating the Subsidy Act
View list
Do you have more questions?






